The person behind Happy Mortgages
Amina Khan
More than a decade in mortgages. Still asking why.
Mortgage Loan Officer · NMLS #1385402 · Charlotte
How I got here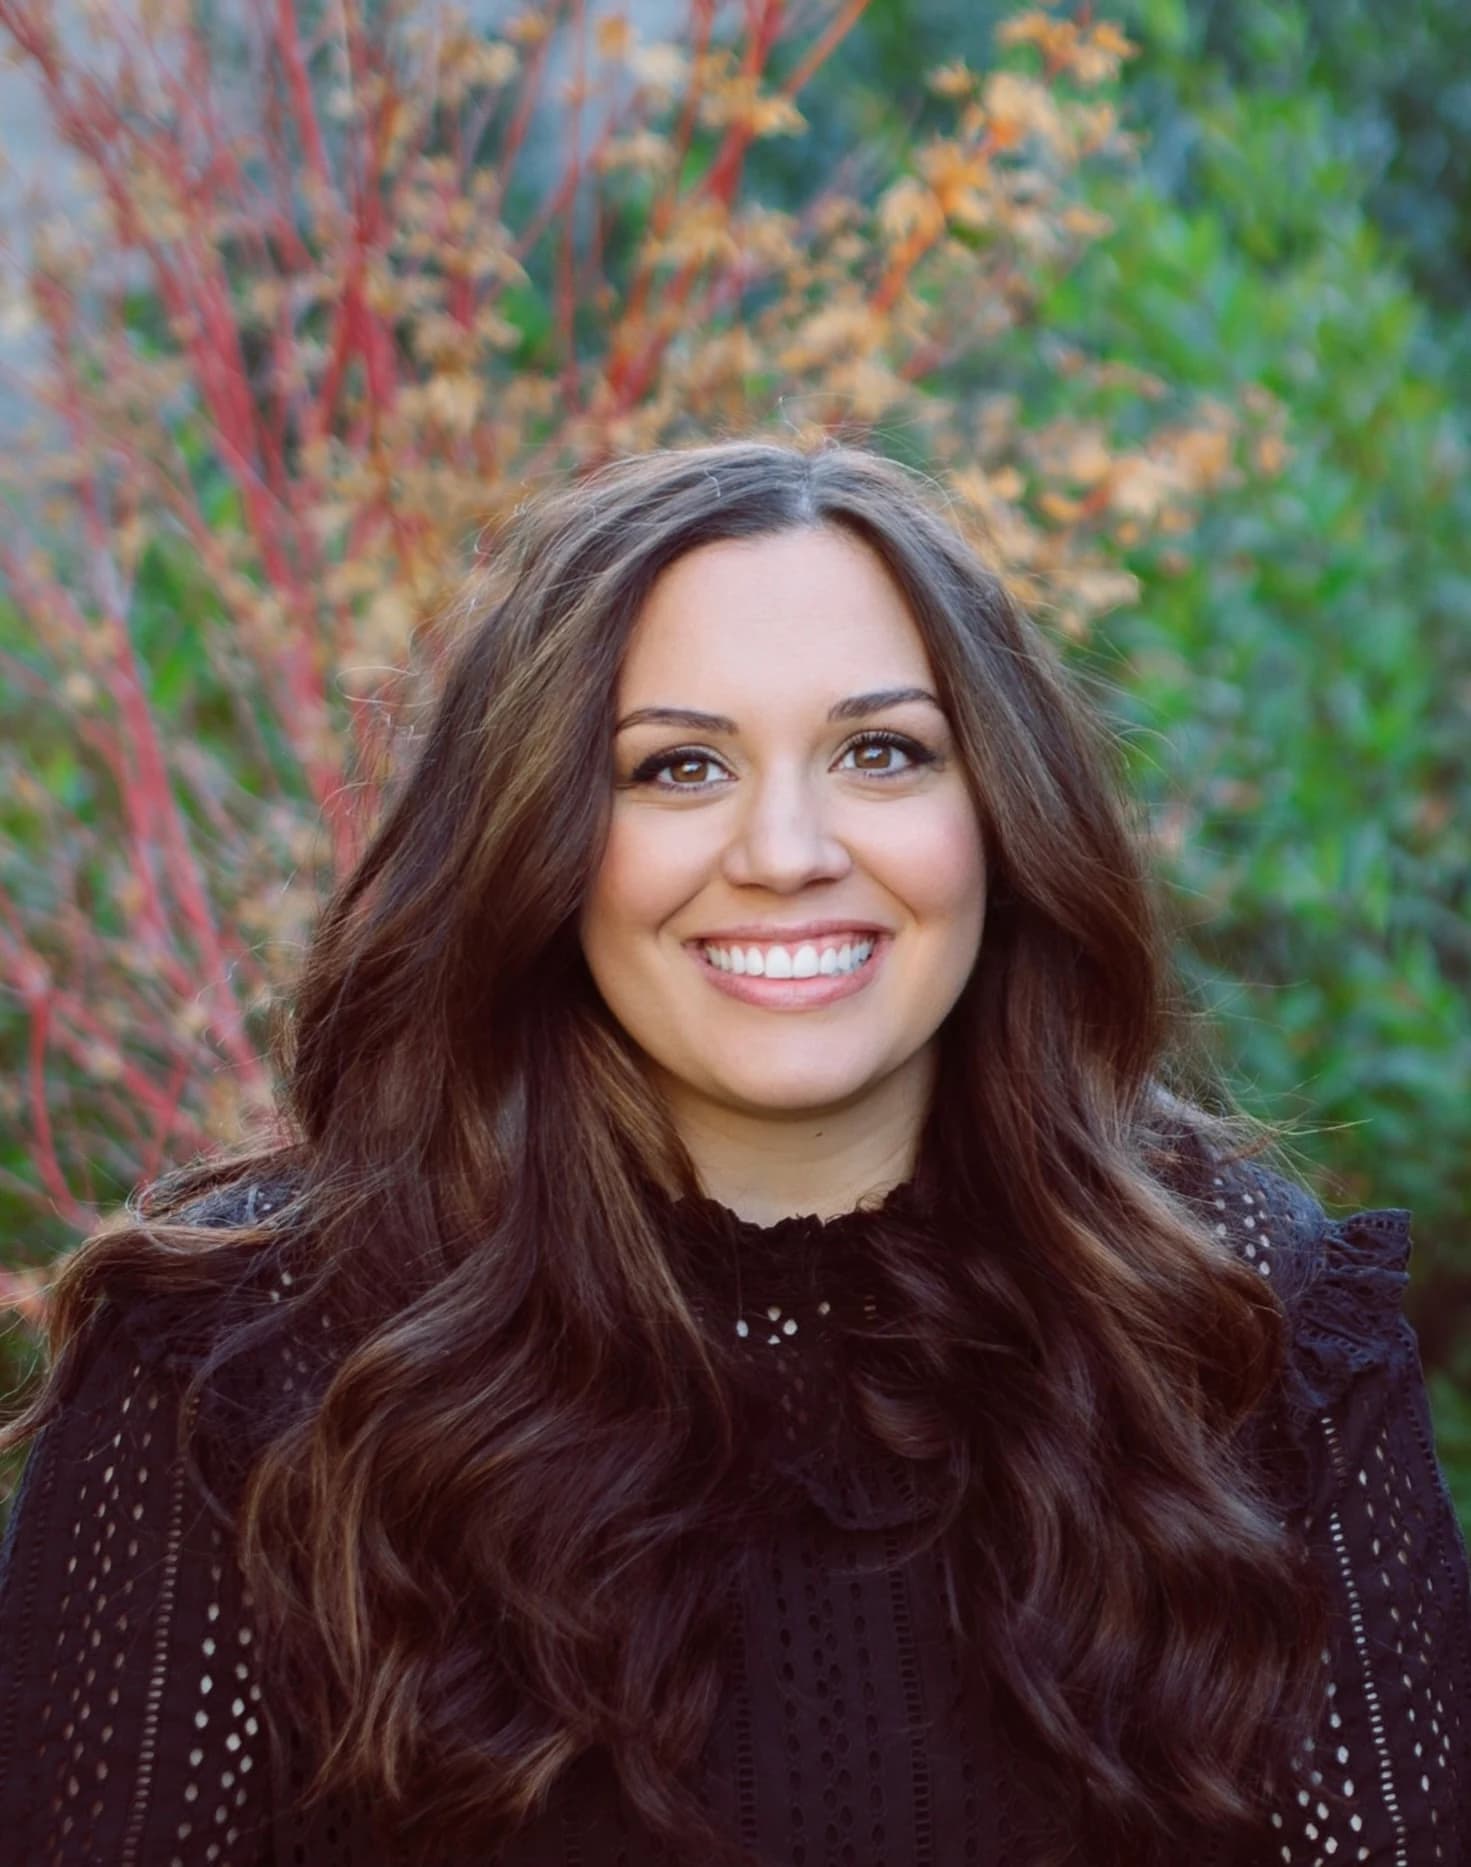
- Mortgage closings seen through to fruition
- 6,000+
- In mortgage lending
- Since 2015
- Retail + operations/builder lending
- 7 years
- Broker lending
- 4+ years
Experience
How I got here
I entered mortgage lending in 2015 and spent the first seven years of my career inside a national retail lender, much of that time working in production management and builder lending.
Over the years, I’ve had a hand in seeing more than 6,000 mortgage closings through to fruition.
That kind of volume teaches you things a guideline alone can’t.
Builder transactions, in particular, can have a lot of moving parts: construction timelines, changing completion dates, rate locks, incentives, contracts and amendments, appraisal timing, buyer qualification, communication across multiple parties, and a closing date that matters to far more people than the borrower and lender.
They require organization, anticipation, and an understanding of how one change can ripple through the rest of the transaction.
That foundation came before I moved into the broker world and began spending more of my time digging deeply into guidelines, alternative documentation, loan structure, and complex borrower scenarios.
The two sides of my experience now work together.
I’ve seen mortgages at scale, and I’ve learned to slow down when an individual file requires it.
Amina Khan, Mortgage Loan Officer
“Complexity isn’t the point. Understanding the entire transaction is.”
Why mortgages
Mortgages sit at the intersection of numbers, people, rules, problem-solving, and real life.
I got into mortgage lending in 2015 and didn’t initially realize how well the work fit my brain.
Over time, I became increasingly interested not just in whether something worked, but why it worked.
Why didn’t it work?
What guideline controlled the answer?
Was the issue permanent, or was it timing?
Did the documentation tell the whole story?
Was there another legitimate way to structure it?
That curiosity changed the way I approach lending.
Why Happy Mortgages
The name is intentionally simple.
“Happy Mortgages isn’t built around persuasion. It’s built around explanation.”
Happy doesn’t mean every file is easy, every answer is yes, or every transaction follows the textbook.
It means the experience should be real, honest, transparent, informed, and unpressured.
You should understand what’s happening, why you’re being asked for something, what your options are, and what happens next.
And part of “happy” is knowing the decision was actually yours. You understood what you were agreeing to, had the information you needed, and weren’t rushed, pressured, or fooled into making it.
That’s real consent. Informed and unpressured.
I don’t think someone can meaningfully consent to a financial decision they don’t understand.
I treat clients like adults. I respect your intelligence, but I don’t expect you to have professional knowledge you’ve had very little reason to possess.
My job is to understand the file, explain what I see, and help you understand the possibilities, limitations, and next steps.
Then?
You decide.
Outside work
A library family
I live in North Carolina, and I’m a mom to twins.
I also come from a family of librarians, which probably explains more than a little about why I somehow ended up building a mortgage library of my own.
Outside work, I’m usually somewhere around family, travel, writing, reading, learning, architecture, art, design, checking out the trees, trying to be more active, or whatever subject has sent me down my latest research rabbit hole.
The details, plainly
My file, for a change
My license is public record. Search my NMLS number at NMLS Consumer Access and you can check it for yourself.
- Name
- Amina Khan
- Role
- Founder, Managing Loan Officer · Individually licensed
- Company
- Happy Mortgages LLC is the brand and company. It is not a licensed mortgage lender or broker; company mortgage licensing is still in progress.
- License
- Mortgage Loan Officer, individually licensed
- What I originate
- Currently originating non-QM financing for investment and second-home properties.
- State licensing
- Listed at the bottom of this page.
Where to next
Send the outline
Tell me what you’re trying to do, and where you’re getting stuck. No documents or credit pull to start.
I usually reply within 48 to 72 hours.